
 Building, completing or improving a home can require a substantial amount of money, especially when construction materials, labour, electrical work, plumbing and finishing costs are considered together. People searching for Akhuwat Loan for Home Apply Online are often looking for a simple way to understand home financing, application preparation and the amount they may need for their project.
This 2026 guide is designed to help families plan a home-related financing requirement ranging from approximately Rs. 50,000 to Rs. 50 lakh, depending on the scale of their project. The amount required by each household can be different, and actual financing availability, approval and limits depend on the applicable program and individual assessment.
Before starting, applicants should focus on three things: the actual purpose of the financing, the estimated construction cost and a realistic repayment capacity. For more general information, visit our Akhuwat Loan Pakistan 2026 guide.
What Is Akhuwat Loan for Home Apply Online?
The term Akhuwat Loan for Home Apply Online is commonly searched by people looking for information about financial assistance for residential needs. These needs may include beginning construction, completing an unfinished house, carrying out essential improvements or managing necessary home-related expenses.
Home financing should always begin with proper planning. A person who needs money for one unfinished room has a very different financial requirement from someone planning a larger construction project. Therefore, the amount should be calculated according to the work rather than selected randomly.
Home Financing Planning From Rs. 50,000 to Rs. 50 Lakh
Different home projects require different budgets. A smaller amount may be sufficient for limited repairs or essential improvements, while larger construction projects can require significantly more capital.
For planning purposes, home-related budgets can range from around Rs. 50,000 up to Rs. 50 lakh. This range should be treated as a budgeting example rather than a guaranteed approval range. The actual amount available through any financing program can depend on its current terms, eligibility rules, location and assessment of the applicant.
Rs. 50,000 to Rs. 2 Lakh
This type of budget may be considered for relatively small home requirements such as essential repairs, limited electrical work, plumbing, paint, doors, windows or completion of a small unfinished section.
Rs. 2 Lakh to Rs. 5 Lakh
A medium-sized budget may help with a room, roof work, flooring, renovation or a combination of material and labour expenses depending on local construction prices.
Rs. 5 Lakh to Rs. 10 Lakh
People planning more substantial construction may estimate a budget within this range. The actual work that can be completed depends heavily on property size, material quality, labour rates and location.
Rs. 10 Lakh to Rs. 25 Lakh
Larger home projects can involve structural construction, multiple rooms, electrical systems, plumbing and finishing. A detailed contractor estimate becomes especially important when the planned budget reaches this level.
Rs. 25 Lakh to Rs. 50 Lakh
A major residential project can potentially require a budget approaching Rs. 50 lakh or more. Anyone considering this level of financing should prepare detailed construction estimates and carefully assess long-term affordability.
Important: These figures illustrate possible project budgets only. They do not mean that every amount is available or that an applicant will be approved for a particular amount.
What Can a Home Financing Budget Cover?
A well-planned home budget can include several different construction categories. Applicants should identify their most important needs before calculating the required amount.
- Foundation and structural construction
- Bricks, cement, sand and steel
- Roof construction or repair
- Room construction
- Electrical wiring and fittings
- Plumbing and water systems
- Doors and windows
- Flooring and tiles
- Plaster and paint
- Kitchen-related construction
- Bathroom construction
- Essential renovation
- Completion of unfinished residential portions
How to Choose the Right Amount
Choosing the correct financing amount is one of the most important parts of home planning. Taking an amount that is too small may leave construction unfinished, while planning for more money than necessary can create unnecessary repayment pressure.
Start by preparing three figures:
- Estimated cost of construction materials
- Estimated labour and contractor expenses
- Additional reserve for unexpected essential expenses
Add these together and compare the total with the savings you can contribute personally. The remaining requirement gives you a more realistic idea of how much financing you need.
Akhuwat Loan for Home Apply Online – Preparation Process
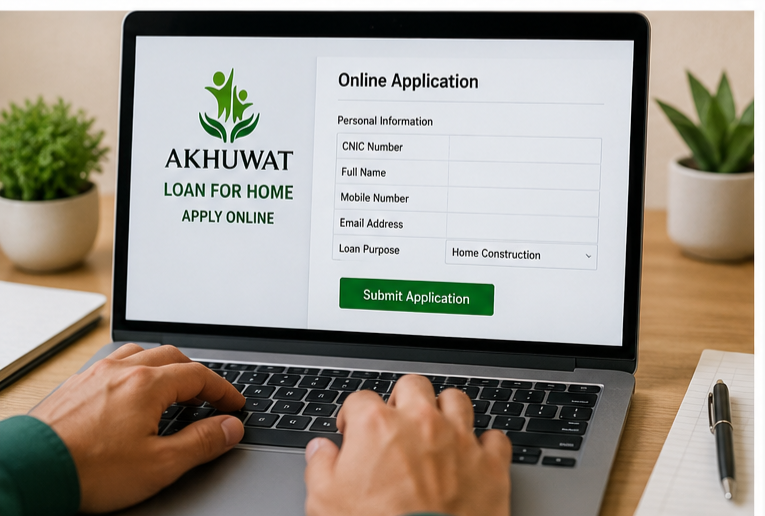
People searching for Akhuwat Loan for Home Apply Online 2026 should prepare their information carefully before beginning any application process.
Step 1: Decide the Purpose
Clearly identify why you need home financing. Your requirement might involve new construction, an unfinished house, essential renovation, additional rooms or another genuine residential need.
Step 2: Prepare Your Construction Estimate
Make a written estimate instead of relying on a rough guess. Ask suppliers about material prices and discuss labour expenses with workers or a contractor.
Step 3: Calculate Your Required Amount
After calculating the complete project cost, subtract any personal savings that you plan to use. This gives you a clearer estimate of the financing gap.
Step 4: Prepare Personal Information
Keep your identity, address, contact and income information organized. Accurate and consistent information makes an application easier to understand and assess.
Step 5: Prepare Supporting Documents
Documents can vary according to the financing arrangement and applicant circumstances. Keeping your paperwork organized beforehand can save time later.
For additional preparation help, read our Akhuwat Loan Documents Checklist 2026.
Step 6: Review the Information
Check names, CNIC details, contact information, income information and construction estimates before submitting an application through the appropriate available channel.
Documents to Keep Ready
People preparing for home-related financing may find it useful to organize the following information and documents where applicable:
- Valid CNIC information
- Active mobile/contact details
- Residential information
- Income or earning information
- Employment or business information where applicable
- Household expense estimate
- Construction budget
- Property-related information where required
- Supporting documents relevant to the application
You can also read our detailed Akhuwat Loan Application Requirements 2026 guide before preparing your application.
How to Make Your Home Budget Stronger
A strong construction budget does not simply contain a total amount. It explains where the money is expected to go.
For example, instead of writing that a house requires Rs. 10 lakh, divide the expected amount between structure, materials, labour, electrical work, plumbing and finishing. This gives you much better control over construction spending.
Structure Budget
Estimate the cost of bricks, cement, steel, sand and other structural materials required for the planned construction.
Labour Budget
Discuss rates before starting work. Understand whether workers will be paid daily, according to completed work or through an agreed project rate.
Electrical and Plumbing Budget
These costs are sometimes underestimated during early construction planning. Wiring, switches, pipes, sanitary fittings and installation charges should be included from the beginning.
Finishing Budget
Flooring, paint, doors, windows and other finishing items can significantly increase total construction costs. Separate essential finishing from optional decorative upgrades.
Monthly Income and Repayment Planning
Before considering a large amount, applicants should understand how future repayments would fit into their normal household budget.
Write down your average monthly income and subtract regular expenses such as:
- Food and household necessities
- Electricity and utility expenses
- Transportation
- Children’s education
- Medical and family expenses
- Existing financial commitments
- Other necessary monthly spending
The amount remaining after essential expenses gives a better indication of how much additional monthly commitment may be manageable.
Should You Apply for the Maximum Amount?
Not necessarily. The right amount is not automatically the largest amount. It is the amount that matches your genuine construction requirement and remains manageable according to your financial position.
If a project requires Rs. 5 lakh, planning for Rs. 20 lakh without a clear need can make financial management more difficult. Similarly, underestimating the project can result in unfinished construction.
Accurate budgeting is therefore more important than simply targeting the highest possible amount.
Home Construction in Different Stages
Families working with a limited budget can divide construction into stages rather than trying to complete the entire property at once.
- Foundation and structural work
- Walls and roofing
- Electrical and plumbing work
- Plaster
- Doors and windows
- Flooring
- Paint and essential finishing
This approach can make a large home project easier to control financially.
How to Reduce Construction Costs
Controlling expenses can reduce the amount of financing required. Small savings across multiple construction categories can produce a meaningful difference in the final project cost.
Get Multiple Material Quotes
Compare prices from several suppliers before purchasing large quantities of cement, steel, bricks or other expensive materials.
Plan Before Construction Starts
Repeated design changes during construction can increase both labour and material expenses. Decide room sizes and essential layouts as early as possible.
Prioritize Essential Work
Structural safety, roofing, water, electricity and essential living areas should generally come before decorative upgrades.
Keep an Expense Record
Record major purchases and labour payments. Comparing actual spending with the original estimate can help prevent the project budget from moving out of control.
Akhuwat Loan for Home Apply Online for Salaried Applicants
Salaried applicants can prepare a monthly budget using their regular income. They should consider their normal household expenses before deciding how much additional financial commitment is manageable.
Keeping income information and household expenses organized can also make the overall financial picture easier to understand.
Akhuwat Loan for Home Apply Online for Business Owners
Self-employed individuals and business owners may have income that changes between months. Instead of using the highest earning month, calculate an average based on several normal months.
This can provide a more realistic picture of repayment capacity. Business owners interested in separate business financing information can also read our Akhuwat Business Loan Complete Guide 2026.
Common Mistakes to Avoid During Home Financing Planning
- Choosing an amount without preparing a construction estimate
- Ignoring labour expenses
- Forgetting electrical and plumbing costs
- Spending heavily on decorative work before essential construction
- Not comparing material prices
- Changing the house design repeatedly
- Using the entire budget without keeping a reserve
- Ignoring monthly repayment affordability
Why Accurate Information Matters
Whether an application is prepared online or through another available channel, information should remain accurate and consistent. Applicants should review personal details, contact information, income information and supporting documents carefully.
For a broader explanation of application stages, see our Akhuwat Loan Process 2026 – Step-by-Step Guide.
Akhuwat Loan for Home Apply Online 2026 – Quick Checklist
Before moving forward, use this checklist to organize your home financing plan:
- Define the exact purpose of the home project.
- Prepare a material cost estimate.
- Calculate labour expenses.
- Add electrical, plumbing and finishing costs.
- Decide how much personal savings you can contribute.
- Calculate the remaining financing requirement.
- Prepare identity and income information.
- Organize relevant property documents.
- Review your monthly household budget.
- Check all application information carefully.
Frequently Asked Questions
What does Akhuwat Loan for Home Apply Online mean?
It is a search term commonly used by people looking for information about home-related financing and application options. Applicants should check the currently available application method and applicable requirements before proceeding.
Can I plan a home project between Rs. 50,000 and Rs. 50 lakh?
Yes, construction projects can vary widely in cost. A small repair may require a relatively limited budget, while major construction can require several lakh rupees. However, a project’s estimated cost should not be confused with a guaranteed financing limit or approval amount.
Can financing be considered for an unfinished house?
People with unfinished residential construction may explore available home-financing options depending on the purpose, applicable requirements and assessment process.
Can I use personal savings with financing?
Using personal savings for part of the project can reduce the amount of external financing required. This can be particularly useful for larger construction projects.
What should I calculate before applying?
Calculate the total construction cost, available personal savings, remaining financial requirement, household income, regular expenses and a comfortable repayment capacity.
What is the best amount to apply for?
There is no single amount suitable for everyone. The appropriate amount should reflect the actual project cost and the applicant’s financial capacity rather than simply being the maximum amount available.
Final Thoughts
People searching for Akhuwat Loan for Home Apply Online should begin with careful financial and construction planning. Whether the home project requires around Rs. 50,000, several lakh rupees or a substantially larger budget, the amount should always be connected to a genuine and clearly calculated construction requirement.
Prepare a complete cost estimate, compare material prices, calculate labour expenses, organize relevant documents and understand how repayments could affect your monthly household budget. Good preparation can make the entire financing decision clearer and help prevent unnecessary financial pressure during construction.
Instead of focusing only on how much financing may be available, focus on how much your home project actually requires. This approach creates a stronger construction plan and a more manageable financial strategy for 2026.
For more information about application preparation, home financing and other loan-related guides, visit our Akhuwat Loan Pakistan homepage. Akhuwat Loan for Home Apply Online 2026